A local guide for homeowners in Mead, Berthoud, Longmont, Firestone, Frederick, Windsor, Loveland, Erie, and nearby Front Range communities.If you are planning to buy another primary residence, you
Dated: September 9 2026
Views: 42
A local guide for homeowners in Mead, Berthoud, Longmont, Firestone, Frederick, Windsor, Loveland, Erie, and nearby Front Range communities.
If you are planning to buy another primary residence, you may not have to sell your current Northern Colorado home first. Depending on your income, debts, equity, current mortgage payment, rental potential, credit profile, cash reserves, and loan program, you may be able to convert your current home into a long-term rental while purchasing your next home.
This can be a useful option for homeowners who are moving up, downsizing, relocating, moving to acreage or a horse property, transitioning closer to family, or simply hoping to keep a home with a favorable existing mortgage.
Fannie Mae updated its departing-residence rental-income guidance effective September 2, 2026. Under eligible circumstances, a lender may be able to use documented market rent for a departing primary residence rather than relying only on an executed lease. The lender generally calculates qualifying rental income using 75% of documented gross market rent, then determines whether that amount offsets the home’s monthly housing expense or is treated as a loss in the borrower’s debt-to-income calculation.
That does not mean every homeowner will qualify, and it does not mean renting is automatically the right financial move. But for the right homeowner and property, it may create another path forward.
A departing residence is the home you currently live in but plan to leave when you buy your next primary residence.
For example, you may currently own a home in Mead, Colorado, and plan to purchase a larger home in Berthoud, a downsized home in Longmont, or an acreage or horse property elsewhere in Northern Colorado. Instead of selling the Mead home, you may decide to retain it as a rental property.
The challenge has historically been that the existing home payment could make it harder to qualify for the next mortgage. Updated Fannie Mae guidance may help eligible borrowers by allowing lenders to consider documented market rent as part of the qualifying analysis.
For an eligible departing residence, Fannie Mae’s guidance generally uses 75% of documented monthly gross market rent to calculate net rental income for mortgage qualification.
Here is a simplified illustration:
In this illustration, the calculated rental amount could potentially offset the payment on the departing residence and create a positive amount for the lender’s income analysis. If the calculation results in a negative amount, that loss is generally included in the debt-to-income calculation instead. Actual qualification depends on the lender’s underwriting review and your complete financial situation.
A qualified lender will determine whether this guidance applies to your loan and how rental income is documented and calculated.
Keeping your current home may be worth exploring if you are:
Moving from a starter home to a larger home for a growing household.
Downsizing but would like to keep a property as a long-term asset.
Relocating within Mead, Berthoud, Longmont, Firestone, Frederick, Windsor, Loveland, Erie, or another Northern Colorado community.
Moving from an in-town home to acreage, a rural property, or a horse property.
Transitioning into retirement, a senior-friendly home, or a home closer to family.
Navigating a divorce or other major life change and evaluating multiple housing options.
Holding a favorable current mortgage rate that you would prefer to keep.
Interested in building a long-term rental asset while purchasing your next primary residence.
The right choice depends on your goals. Some homeowners value immediate equity and a simpler move. Others prefer to hold real estate long term and are comfortable with the responsibilities of ownership and leasing.
A home that can rent does not automatically make it a good rental investment. Before deciding whether to sell or rent, it is important to look at the full picture.
A strong sell-versus-rent analysis should include:
For a Northern Colorado homeowner, the decision should be based on a realistic—not overly optimistic—rental estimate. A local rental analysis should account for the property’s location, size, condition, features, school area, seasonality, current competing rental inventory, HOA restrictions, and recent rental comparables.
Online rent estimates can be a helpful starting point, but they should not be the only number used for a major financing or investment decision.
Imagine a homeowner who owns a home in Mead and is considering purchasing an acreage property outside Berthoud or a horse property in Northern Colorado.
They may have meaningful equity in the Mead home and a favorable existing mortgage payment. Keeping that home as a rental could potentially provide a long-term asset while allowing them to make their next move.
However, the household still needs to qualify for the new mortgage, document appropriate market rent, maintain the required reserves, and prepare for real-world landlord expenses such as repairs, insurance changes, tenant turnover, vacancy, and potential property-management costs.
This is why a sale-versus-rent decision should be made with both local real estate information and qualified lending guidance—not just an online rental estimate.
Mortgage qualification is always personal and property-specific. Even when documented market rent may be used, lenders still review the full borrower profile and applicable loan requirements.
That review may include:
Employment, income, assets, debts, and credit profile.
The payment on the current home and the payment on the next home.
Documented market rent and the lender’s calculation of qualifying rental income.
Available cash reserves.
Property type, condition, location, and HOA rental policies.
Existing rental-property ownership or rental-management experience.
Loan-program guidelines and lender-specific underwriting overlays.
For borrowers with less than 12 months of rental-property management experience, Fannie Mae’s guidance may require six months of reserves for the departing residence. A lender must evaluate the applicable requirements for your circumstances.
This article is for general educational purposes only and is not lending, tax, legal, or investment advice. A qualified mortgage lender, tax professional, attorney, insurance professional, and—when appropriate—property manager can help you evaluate the details of your situation.
Possibly. Your ability to purchase another home while retaining your current home as a rental depends on your income, debt, credit, assets, existing housing payment, estimated market rent, required reserves, loan program, and lender underwriting. A qualified lender should review your full situation before you decide whether to sell, rent, or buy.
Under Fannie Mae’s departing-residence guidance updated September 2, 2026, an eligible borrower may be able to use documented market rent rather than relying only on an executed lease. The lender must still document the rental-income amount and apply all relevant underwriting requirements.
For an eligible departing residence, Fannie Mae’s guidance generally uses 75% of documented monthly gross market rent to calculate net rental income. The lender then determines whether that amount offsets the current home’s full monthly housing expense or creates a loss that must be included in debt-to-income calculations.
A local rental analysis should consider recently leased comparable homes, your neighborhood, square footage, number of bedrooms and bathrooms, overall condition, amenities, school area, HOA requirements, tenant demand, seasonality, and competing rental inventory. A local real estate professional can help you estimate a realistic rental range, while a lender determines how market rent can be used for loan qualification.
There is no one-size-fits-all answer. Selling may provide immediate access to equity and simplify your move. Keeping the home as a rental may preserve a long-term asset and potentially create income, but it also comes with maintenance, vacancy, tenant, insurance, tax, management, and financing considerations. A side-by-side sell-versus-rent analysis can make the tradeoffs clearer.
If you are planning a move in Mead or Northern Colorado and wondering whether to sell your current home or keep it as a rental, let’s evaluate the numbers before you make a decision.
I can help you compare estimated sale proceeds with a realistic local rental range, review property-specific considerations such as HOA rental policies and tenant appeal, and connect you with a qualified local lender to review financing options.
Together, we can build a clear sell-versus-rent plan around your next move—whether you are relocating, moving up, downsizing, transitioning to acreage, or purchasing a horse property.
Contact Laura Owen for a Northern Colorado sell-versus-rent consultation.
About Laura Owen: Laura Owen is a Northern Colorado residential real estate agent serving Longmont and surrounding Front Range communities. A REALTOR® since 2014, Laura helps homeowners and buyers navigate relocation, acreage and horse-property purchases, senior transitions, divorce-related housing decisions, and sell-versus-rent planning. She provides local market guidance and connects clients with qualified lending, tax, legal, insurance, and property-management professionals when appropriate.
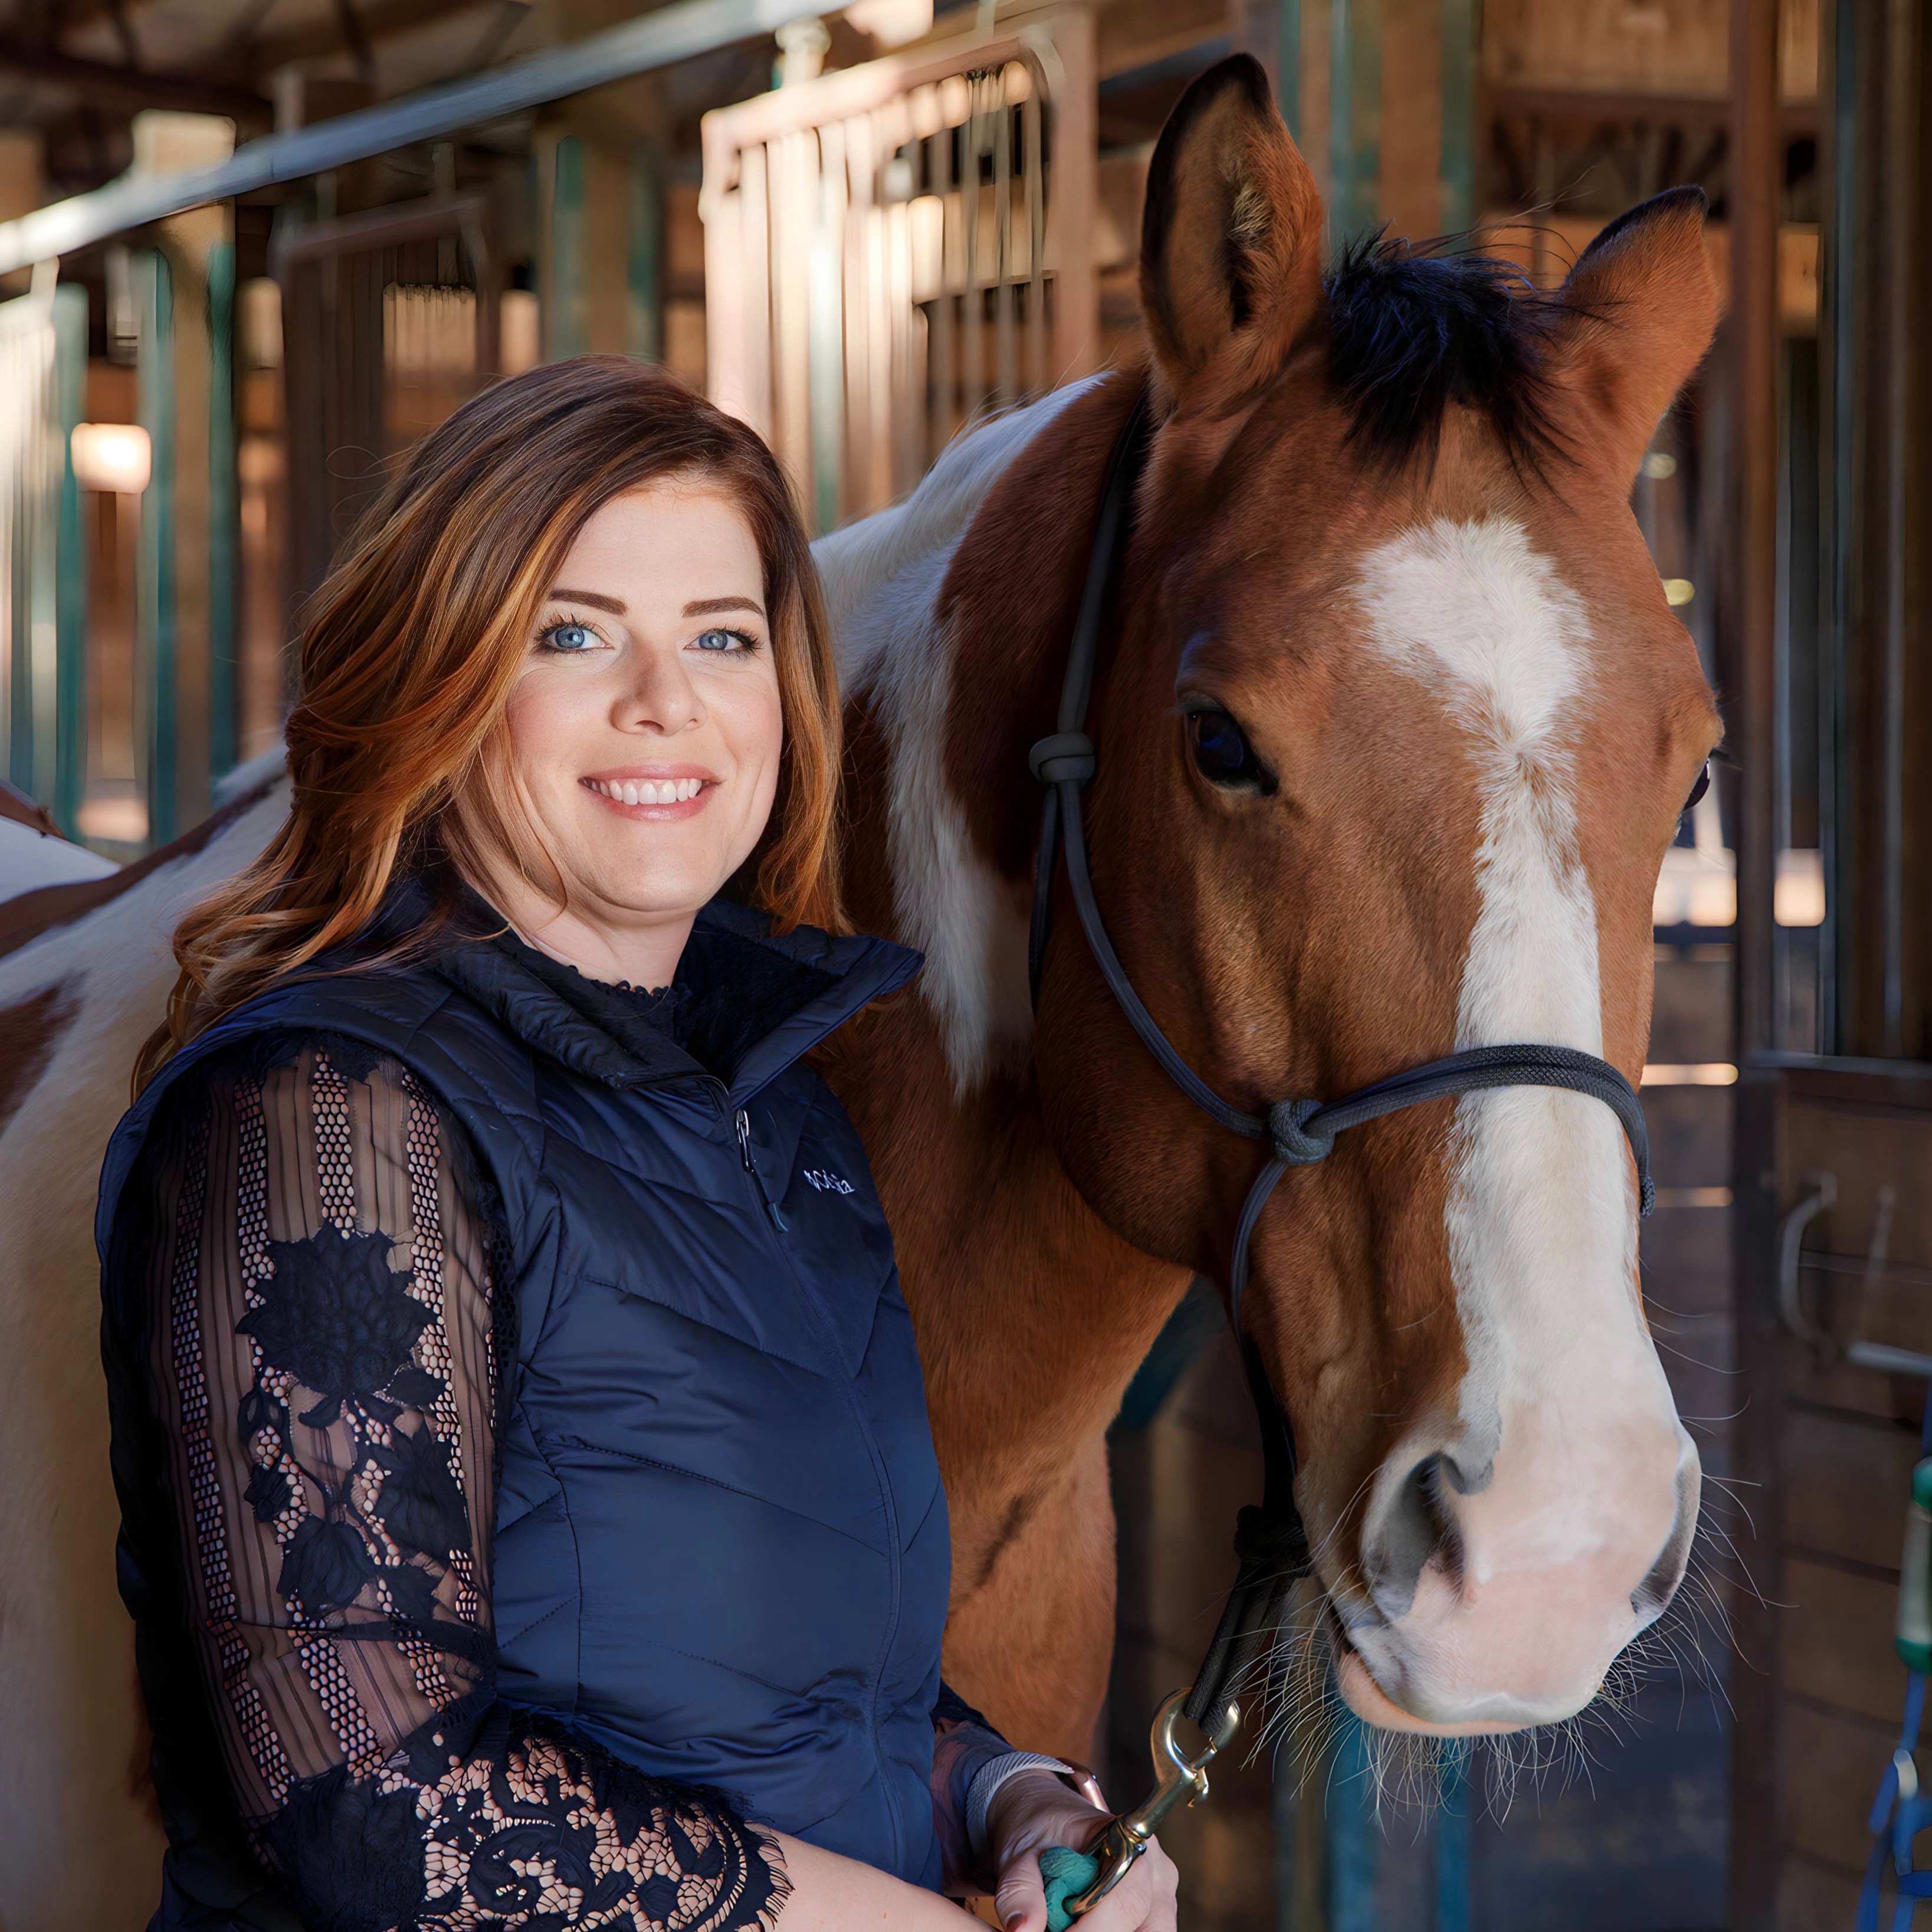
Laura Owen, REALTOR® with RE/MAX Momentum, is a lifelong Front Range resident who combines local knowledge with over 20 years in the real estate industry, including 11 years as a licensed REALTOR®. ....
A local guide for homeowners in Mead, Berthoud, Longmont, Firestone, Frederick, Windsor, Loveland, Erie, and nearby Front Range communities.If you are planning to buy another primary residence, you
Commerce City Townhome Offers a Convenient Start in the Denver Metro AreaHomeownership in the Denver metro area can feel out of reach for buyers who want a comfortable home, outdoor space, and
An Attractive Entry Point to Denver Metro Homeownership: Commerce City Townhome Near DIAFor buyers who want to put down roots in the Denver metro area without taking on the upkeep of a large single
7 HOA Checklist Items Every Homebuyer Should Review Before BuyingBuying a home in an HOA community can be a smart move, especially in Westminster, Broomfield, Arvada, Thornton, Northglenn, Erie,
 The content relating to real estate for sale in this Web site comes in part from the Internet Data eXchange (IDX) program of METROLIST, INC., DBA RECOLORADO©. Real estate listings held by brokers other than Owen Group are marked with the IDX Logo. This information is being provided for the consumers' personal, non-commercial use and may not be used for any other purpose. All information subject to change and should be independently verified. September 25, 2026 1:37 AM UTCd
1. This
publication is designed to provide information regarding the subject matter covered. It is displayed with the understanding that the publisher and authors are not engaged in rendering real estate, legal, accounting, tax, or other professional services and that the publisher and authors are not offering such advice in this publication. If real estate, legal, or other expert assistance is required, the services of a competent, professional person should be sought.
2. The information contained in this publication is subject to change without notice.
METROLIST, INC., DBA RECOLORADO MAKES NO WARRANTY OF ANY KIND WITH REGARD TO THIS MATERIAL, INCLUDING, BUT NOT LIMITED TO, THE IMPLIED WARRANTIES OF MERCHANTABILITY AND FITNESS FOR A PARTICULAR PURPOSE. METROLIST, INC., DBA RECOLORADO SHALL NOT BE LIABLE FOR ERRORS CONTAINED HEREIN OR FOR ANY DAMAGES IN CONNECTION WITH THE FURNISHING, PERFORMANCE, OR USE OF THIS MATERIAL.
3. PUBLISHER'S NOTICE:
All real estate advertised herein is subject to the Federal Fair Housing Act and the Colorado Fair Housing Act, which Acts make it illegal to make or publish any advertisement that indicates any preference, limitation, or discrimination based on race, color, religion, sex, handicap, familial status, or national origin.
4. METROLIST, INC., DBA RECOLORADO will not knowingly accept any advertising for real estate that is in violation of the law. All persons are hereby informed that all dwellings advertised are available on an equal opportunity basis.
5. 
6. © 2026 METROLIST, INC., DBA RECOLORADO© - All Rights Reserved
6455 S. Yosemite St., Suite 500
Greenwood Village, CO 80111 USA
7. ALL RIGHTS RESERVED WORLDWIDE. No part of this publication may be reproduced, adapted, translated, stored in a retrieval system or transmitted in any form or by any means, electronic, mechanical, photocopying, recording, or otherwise, without the prior written permission of the publisher. The information contained herein including but not limited to all text, photographs, digital images, virtual tours, may be seeded and monitored for protection and tracking.
Options
Show More...
 Information deemed reliable but not guaranteed by the MLS. © 2026 Information and Real Estate Services, LLC.
Information source: Information and Real Estate Services, LLC. Provided for limited non-commercial use only under IRES Rules. © Copyright IRES.
The information being provided is for the consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumer may be interested in purchasing.
The IRES, LLC Data on this
site was last updated: September 25, 2026 1:43 AM UTC
This site is used and paid for by multiple independent companies. The real estate broker cannot require you as a prospective buyer to pre-qualify with or utilize the services of either of the mortgage loan originators. Nor can either of the mortgage load originators require you as a prospective buyer to utilize the services of the real estate broker.
Show More...
