A local guide for homeowners in Mead, Berthoud, Longmont, Firestone, Frederick, Windsor, Loveland, Erie, and nearby Front Range communities.If you are planning to buy another primary residence, you
Dated: February 17 2026
Views: 17
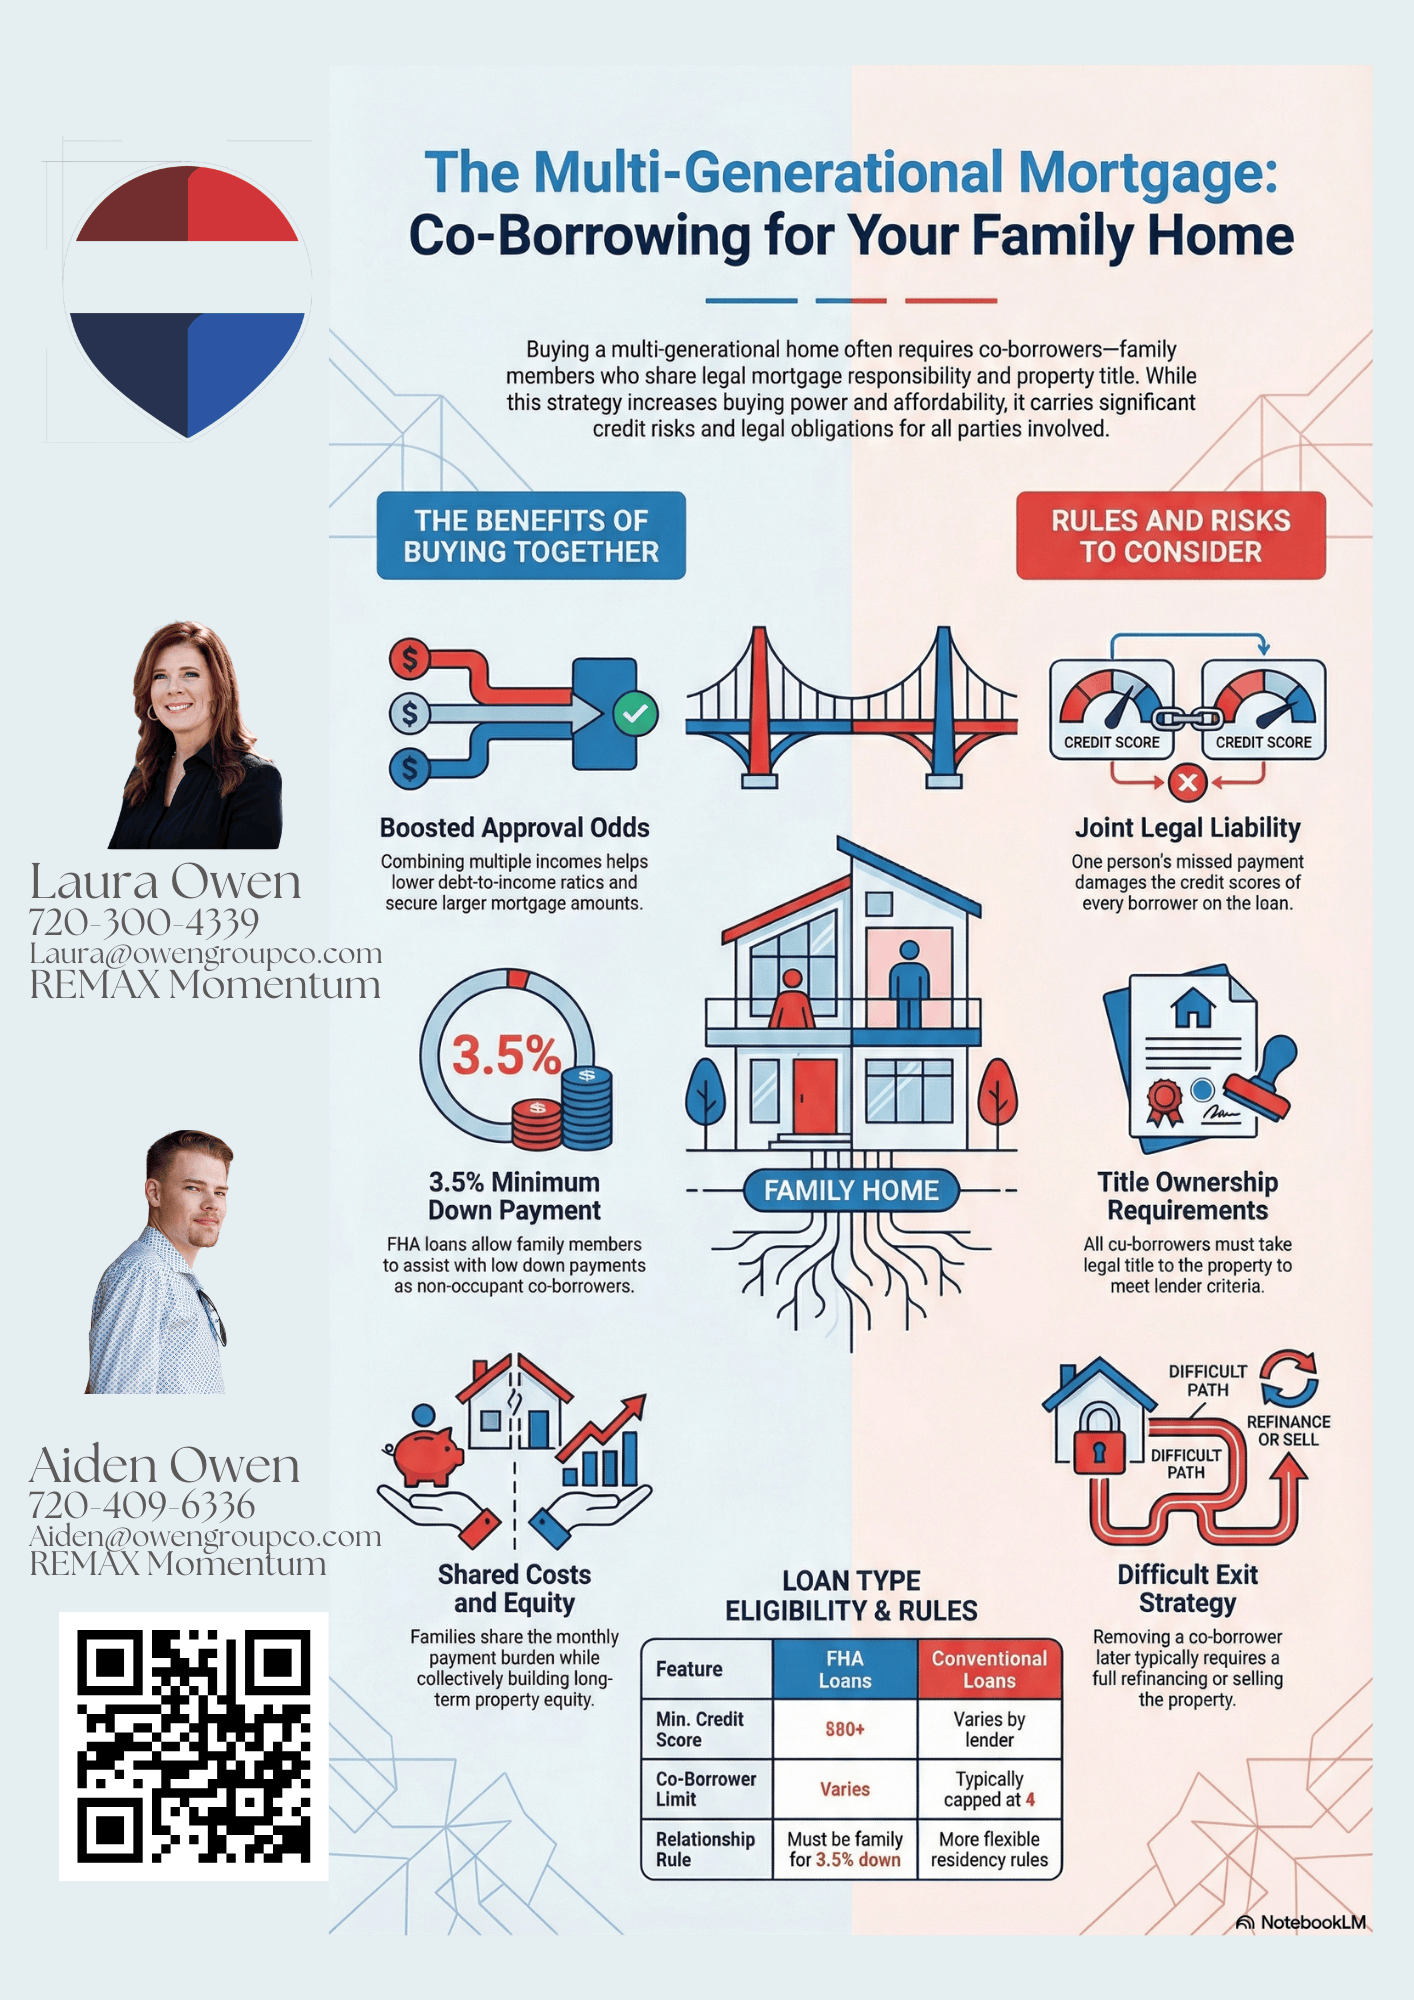
Buying a home with family has become increasingly common, especially as housing prices rise and families choose to live together across generations. One way to make that possible is by purchasing a property with a co-borrower—someone who shares equal legal and financial responsibility for the mortgage. But before signing together, it’s important to understand the rules, benefits, and risks involved.
What Is a Co-Borrower?
A co-borrower shares not only the mortgage debt but also the ownership of the property. In a multi-generational purchase, this often means parents and adult children—or sometimes grandparents—pooling income and assets to qualify for a larger or more suitable home.
Key Rules to Know
Lenders treat co-borrowers as equal applicants, so both (or all) must meet standard mortgage criteria:
Credit and income requirements: All borrowers’ credit scores, income, and debt ratios are reviewed together. FHA loans generally require a 580+ credit score, while conventional loans may demand higher.
Title ownership: Every co-borrower is on the property title. FHA loans specifically require this for all co-borrowers.
Eligible relationships: For FHA loans, non-occupant co-borrowers—family members who help qualify but don’t live in the home—must be related by blood, marriage, or legal guardianship.
Borrower limits: Conventional lenders typically cap co-borrowers at four per loan.
No financial interest in the sale: Co-borrowers cannot also be the seller, real estate agent, or anyone profiting from the transaction.
These safeguards help protect both the lender and all involved parties.
The Benefits
Pooling financial resources has clear advantages—especially when affordability is tight or families want to invest together long-term.
Higher buying power: Combined incomes improve mortgage approval odds and increase eligible loan amounts.
Access to better properties: Partners can afford larger homes or homes in more desirable areas.
Better rates: Stronger collective credit can lead to lower interest rates.
Shared financial responsibility: When payments are split among multiple contributors, the burden eases for everyone.
Family-focused ownership: Multi-generational living can help support aging parents or young adults starting fresh while building shared equity.
The Risks
While co-borrowing offers financial and lifestyle perks, it also carries commitments and complications that families must plan for carefully.
Joint liability: Every borrower is equally responsible for monthly payments and loan defaults. A missed payment affects all credit scores.
Difficult to unwind: Removing a co-borrower requires refinancing or selling the property—both can be costly and time-consuming.
Family disagreements: Relationship changes or disputes may lead to ownership conflicts, especially when one co-owner lives in the home and the other does not.
Equity rights: Non-occupant co-borrowers still gain legal ownership stakes, which could cause friction later.
Additional lender restrictions: Some lenders require larger cash reserves or cap debt-to-income ratios at around 50–57% for multi-borrower loans.
Final Thoughts
Using a co-borrower can be a powerful tool for families planning a multi-generational move—but it's not a decision to take lightly. Before applying together, discuss long-term plans, ownership intentions, and exit strategies. With proper guidance and communication, co-borrowing can open doors to homeownership opportunities that benefit the entire family.
Laura Owen, REALTOR® with RE/MAX Momentum, is a lifelong Front Range resident who combines local knowledge with over 20 years in the real estate industry, including 11 years as a licensed REALTOR®. ....
A local guide for homeowners in Mead, Berthoud, Longmont, Firestone, Frederick, Windsor, Loveland, Erie, and nearby Front Range communities.If you are planning to buy another primary residence, you
Commerce City Townhome Offers a Convenient Start in the Denver Metro AreaHomeownership in the Denver metro area can feel out of reach for buyers who want a comfortable home, outdoor space, and
An Attractive Entry Point to Denver Metro Homeownership: Commerce City Townhome Near DIAFor buyers who want to put down roots in the Denver metro area without taking on the upkeep of a large single
7 HOA Checklist Items Every Homebuyer Should Review Before BuyingBuying a home in an HOA community can be a smart move, especially in Westminster, Broomfield, Arvada, Thornton, Northglenn, Erie,
 The content relating to real estate for sale in this Web site comes in part from the Internet Data eXchange (IDX) program of METROLIST, INC., DBA RECOLORADO©. Real estate listings held by brokers other than Owen Group are marked with the IDX Logo. This information is being provided for the consumers' personal, non-commercial use and may not be used for any other purpose. All information subject to change and should be independently verified. September 27, 2026 1:30 AM UTCd
1. This
publication is designed to provide information regarding the subject matter covered. It is displayed with the understanding that the publisher and authors are not engaged in rendering real estate, legal, accounting, tax, or other professional services and that the publisher and authors are not offering such advice in this publication. If real estate, legal, or other expert assistance is required, the services of a competent, professional person should be sought.
2. The information contained in this publication is subject to change without notice.
METROLIST, INC., DBA RECOLORADO MAKES NO WARRANTY OF ANY KIND WITH REGARD TO THIS MATERIAL, INCLUDING, BUT NOT LIMITED TO, THE IMPLIED WARRANTIES OF MERCHANTABILITY AND FITNESS FOR A PARTICULAR PURPOSE. METROLIST, INC., DBA RECOLORADO SHALL NOT BE LIABLE FOR ERRORS CONTAINED HEREIN OR FOR ANY DAMAGES IN CONNECTION WITH THE FURNISHING, PERFORMANCE, OR USE OF THIS MATERIAL.
3. PUBLISHER'S NOTICE:
All real estate advertised herein is subject to the Federal Fair Housing Act and the Colorado Fair Housing Act, which Acts make it illegal to make or publish any advertisement that indicates any preference, limitation, or discrimination based on race, color, religion, sex, handicap, familial status, or national origin.
4. METROLIST, INC., DBA RECOLORADO will not knowingly accept any advertising for real estate that is in violation of the law. All persons are hereby informed that all dwellings advertised are available on an equal opportunity basis.
5. 
6. © 2026 METROLIST, INC., DBA RECOLORADO© - All Rights Reserved
6455 S. Yosemite St., Suite 500
Greenwood Village, CO 80111 USA
7. ALL RIGHTS RESERVED WORLDWIDE. No part of this publication may be reproduced, adapted, translated, stored in a retrieval system or transmitted in any form or by any means, electronic, mechanical, photocopying, recording, or otherwise, without the prior written permission of the publisher. The information contained herein including but not limited to all text, photographs, digital images, virtual tours, may be seeded and monitored for protection and tracking.
Options
Show More...
 Information deemed reliable but not guaranteed by the MLS. © 2026 Information and Real Estate Services, LLC.
Information source: Information and Real Estate Services, LLC. Provided for limited non-commercial use only under IRES Rules. © Copyright IRES.
The information being provided is for the consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumer may be interested in purchasing.
The IRES, LLC Data on this
site was last updated: September 27, 2026 1:47 AM UTC
This site is used and paid for by multiple independent companies. The real estate broker cannot require you as a prospective buyer to pre-qualify with or utilize the services of either of the mortgage loan originators. Nor can either of the mortgage load originators require you as a prospective buyer to utilize the services of the real estate broker.
Show More...
