A local guide for homeowners in Mead, Berthoud, Longmont, Firestone, Frederick, Windsor, Loveland, Erie, and nearby Front Range communities.If you are planning to buy another primary residence, you
Dated: April 10 2026
Views: 52
Be honest. Have you started scrolling Zillow or touring open houses in Frederick or Erie just to get a feel for the market? If you have, it's already time to get pre-approved.
I talk to buyers all the time who are "just looking." That's totally fine. But the moment a house catches your eye, you need to be ready. Northern Colorado's market doesn't wait around. Here's why getting pre-approved before you fall in love is the smartest move you can make.
No matter what you've heard, getting pre-approved doesn't mean you're signing anything or rushing into a purchase. What it does mean is that you know your numbers. And knowing your numbers changes everything about how you search.
During the pre-approval process, a lender reviews your income, debts, credit score, and more. Once you have that number, your search gets focused fast. You're not scrolling through homes you can't afford or passing up ones you actually can.
Here in Longmont, with a median home price right around $534,900, that clarity matters a lot. There's a meaningful difference between homes at $475K and $575K. Knowing exactly where you stand keeps you shopping in the right range and avoids the heartbreak of falling for something out of reach.
$534,900 Longmont Median Home Price January 2026 | 2.07 Months of Housing Supply Longmont — Early 2026 |
Sources: Houzeo — 2026
This is how so many home searches play out. You start scrolling just to see what's out there, and then it happens. You find a house in Berthoud or a townhome in Erie that checks every box. You're in love.
If you're already pre-approved? You're probably in great shape. But if you're not, you now have to scramble. Find a lender. Pull together two years of tax returns, recent pay stubs, bank statements. Submit the paperwork. Wait.
And while you're waiting to hear back, someone else who came prepared can make an offer. As Bankrate explains:
"The best time to get a mortgage preapproval is before you start looking for a home. If you find a home you love but don't have a preapproval in hand, you likely won't have time to get preapproved before you need to make an offer..." — Bankrate |
In a balanced market like NoCo right now, well-priced homes still move. According to Dwellings Colorado, Longmont's average days on market dropped from 74 days to 58 days in 2025 for single-family homes. That's a meaningful shift, and it tells me that buyers aren't dawdling when something looks right.
You can't control when the right home shows up. But you can be ready for it. Think of pre-approval like showing up to the starting line with your shoes tied and your warmup done. Everyone else is still looking for parking.
Laura's local take: I've seen buyers lose houses in Longmont and Frederick over a weekend because they weren't pre-approved. The home gets listed Friday, gets multiple showings Saturday, and the seller accepts an offer Sunday. If you're still scrambling to find a lender on Monday, it's already gone. Get this done now, before you fall in love. |
Pre-approvals don't last forever. So it's worth asking your lender upfront how long yours is valid. As The Mortgage Reports explains:
"Mortgage preapproval letters are typically valid for anywhere from 30 to 90 days. However, a preapproval can be updated and extended if the lender re-checks your information." — The Mortgage Reports |
The good news: refreshing is usually quick if your financial situation hasn't changed much. So if you get pre-approved now and your search takes a couple of months, a simple check-in with your lender keeps you current.
You don't have to be ready to buy to be ready to buy. Getting pre-approved means you've done the homework, you know your number, and when something catches your eye in Firestone or Fort Collins, you can actually go for it.
Here's something specific to our market that buyers often don't know about. If you're buying in Longmont or Boulder County, the City has a Down Payment Assistance program that can genuinely change what's possible for first-time buyers. And according to the City of Longmont, a pre-approval letter is required just to apply.
Skipping pre-approval doesn't just slow you down. For buyers who qualify for DPA, it can mean missing out on assistance that makes a real difference at closing.
Colorado also has statewide programs through CHFA (Colorado Housing and Finance Authority) that offer down payment assistance and favorable loan terms for eligible buyers across the Front Range. These programs require pre-approval as well. The earlier you start the process, the more options you keep open.
Laura's local take: A lot of buyers I work with don't realize that Longmont has its own down payment help, separate from state programs. I always encourage people to explore this early, because the pre-approval you need for your mortgage doubles as your ticket into those programs. Two birds, one step. |
Pre-approval is step one, but there's more to the picture. If you're a first-time buyer, understanding the full process before you start searching makes everything less stressful. The good news is you don't have to figure it out alone.
I work with a lot of buyers in Longmont, Erie, and the Carbon Valley area who are buying for the first time. There's a learning curve, but once you have your pre-approval in hand and a clear plan, the process is a lot more manageable than most people expect.
When should I get pre-approved for a mortgage?
Before you start seriously browsing — even if buying still feels like a "someday" plan. In Northern Colorado, well-priced homes in places like Longmont and Erie can receive offers within a few days of listing. Being pre-approved means you're ready the moment something clicks.
How long does a mortgage pre-approval last?
Most pre-approval letters are valid for 30 to 90 days. If your search takes longer, most lenders can refresh it by re-checking your finances. Ask your lender upfront so you're not caught off guard.
Does getting pre-approved mean I have to buy?
Not at all. A pre-approval is simply your lender verifying your finances and confirming what you qualify for. You're not committed to anything. It just means that when the right home comes along, you're ready to move.
Is a pre-approval required for Longmont's Down Payment Assistance program?
Yes. The City of Longmont requires a pre-approval letter and a completed loan application (Form 1003) to apply for its Down Payment Assistance program, which offers deferred loans and low-interest financing for eligible buyers in Longmont and Boulder County. Getting pre-approved early keeps these programs available to you.
Ask yourself this: if the right home in Longmont, Frederick, or Berthoud showed up tomorrow, would you be ready to make an offer?
If the answer is no, pre-approval is your next step. It doesn't mean you're rushing. It means that when the moment comes, you won't be scrambling.
I'll walk you through the pre-approval process, connect you with trusted local lenders, and make sure you're set up to move when the right home shows up.
Let's Talk — I'm Here to HelpOr visit owengroupco.com
The information and opinions in this article are for general informational purposes only and should not be construed as investment advice. Always conduct your own research and consult a qualified professional before making any real estate or financial decision. The Owen Group makes no guarantees regarding the accuracy or completeness of this content and is not liable for any decisions made in reliance on it.
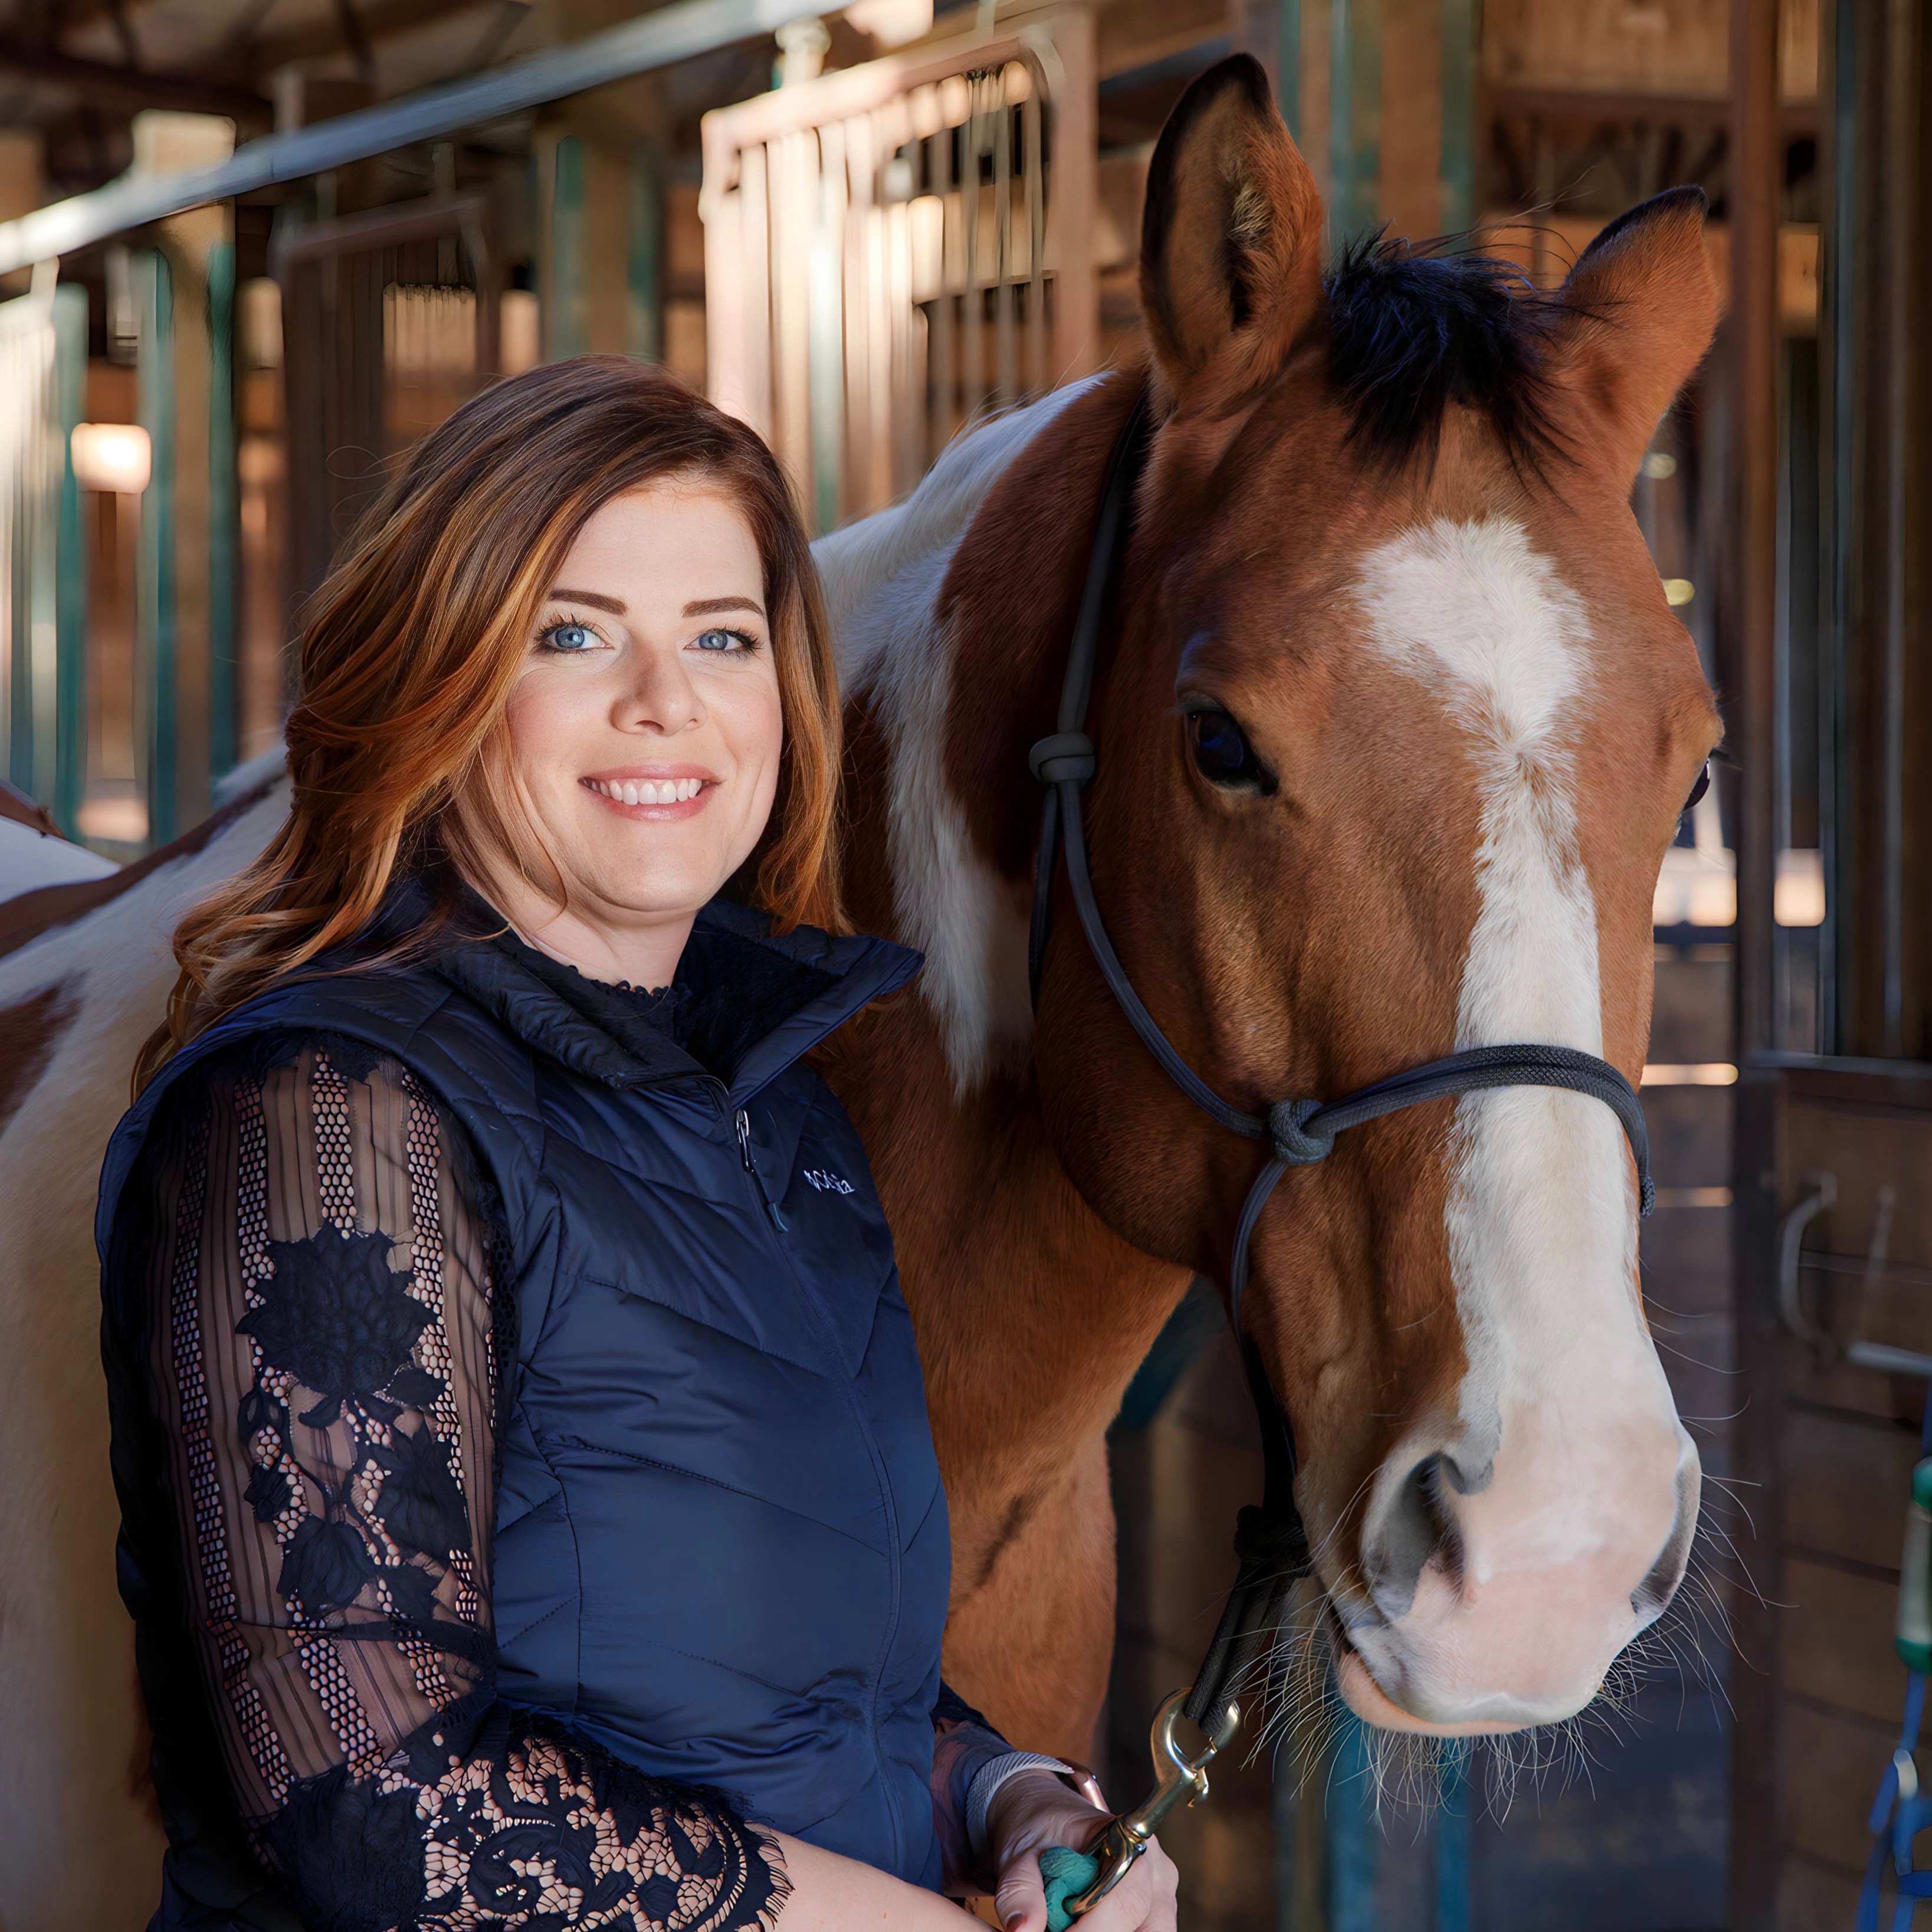
Laura Owen, REALTOR® with RE/MAX Momentum, is a lifelong Front Range resident who combines local knowledge with over 20 years in the real estate industry, including 11 years as a licensed REALTOR®. ....
A local guide for homeowners in Mead, Berthoud, Longmont, Firestone, Frederick, Windsor, Loveland, Erie, and nearby Front Range communities.If you are planning to buy another primary residence, you
Commerce City Townhome Offers a Convenient Start in the Denver Metro AreaHomeownership in the Denver metro area can feel out of reach for buyers who want a comfortable home, outdoor space, and
An Attractive Entry Point to Denver Metro Homeownership: Commerce City Townhome Near DIAFor buyers who want to put down roots in the Denver metro area without taking on the upkeep of a large single
7 HOA Checklist Items Every Homebuyer Should Review Before BuyingBuying a home in an HOA community can be a smart move, especially in Westminster, Broomfield, Arvada, Thornton, Northglenn, Erie,
 The content relating to real estate for sale in this Web site comes in part from the Internet Data eXchange (IDX) program of METROLIST, INC., DBA RECOLORADO©. Real estate listings held by brokers other than Owen Group are marked with the IDX Logo. This information is being provided for the consumers' personal, non-commercial use and may not be used for any other purpose. All information subject to change and should be independently verified. September 27, 2026 1:30 AM UTCd
1. This
publication is designed to provide information regarding the subject matter covered. It is displayed with the understanding that the publisher and authors are not engaged in rendering real estate, legal, accounting, tax, or other professional services and that the publisher and authors are not offering such advice in this publication. If real estate, legal, or other expert assistance is required, the services of a competent, professional person should be sought.
2. The information contained in this publication is subject to change without notice.
METROLIST, INC., DBA RECOLORADO MAKES NO WARRANTY OF ANY KIND WITH REGARD TO THIS MATERIAL, INCLUDING, BUT NOT LIMITED TO, THE IMPLIED WARRANTIES OF MERCHANTABILITY AND FITNESS FOR A PARTICULAR PURPOSE. METROLIST, INC., DBA RECOLORADO SHALL NOT BE LIABLE FOR ERRORS CONTAINED HEREIN OR FOR ANY DAMAGES IN CONNECTION WITH THE FURNISHING, PERFORMANCE, OR USE OF THIS MATERIAL.
3. PUBLISHER'S NOTICE:
All real estate advertised herein is subject to the Federal Fair Housing Act and the Colorado Fair Housing Act, which Acts make it illegal to make or publish any advertisement that indicates any preference, limitation, or discrimination based on race, color, religion, sex, handicap, familial status, or national origin.
4. METROLIST, INC., DBA RECOLORADO will not knowingly accept any advertising for real estate that is in violation of the law. All persons are hereby informed that all dwellings advertised are available on an equal opportunity basis.
5. 
6. © 2026 METROLIST, INC., DBA RECOLORADO© - All Rights Reserved
6455 S. Yosemite St., Suite 500
Greenwood Village, CO 80111 USA
7. ALL RIGHTS RESERVED WORLDWIDE. No part of this publication may be reproduced, adapted, translated, stored in a retrieval system or transmitted in any form or by any means, electronic, mechanical, photocopying, recording, or otherwise, without the prior written permission of the publisher. The information contained herein including but not limited to all text, photographs, digital images, virtual tours, may be seeded and monitored for protection and tracking.
Options
Show More...
 Information deemed reliable but not guaranteed by the MLS. © 2026 Information and Real Estate Services, LLC.
Information source: Information and Real Estate Services, LLC. Provided for limited non-commercial use only under IRES Rules. © Copyright IRES.
The information being provided is for the consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumer may be interested in purchasing.
The IRES, LLC Data on this
site was last updated: September 27, 2026 1:47 AM UTC
This site is used and paid for by multiple independent companies. The real estate broker cannot require you as a prospective buyer to pre-qualify with or utilize the services of either of the mortgage loan originators. Nor can either of the mortgage load originators require you as a prospective buyer to utilize the services of the real estate broker.
Show More...
